Budgeting for Pet Owners: Build a Plan That Protects Care
A pet budget should do more than cover kibble, litter, and the occasional new toy. It should give us a clear plan for routine care, surprise expenses, and the decisions that otherwise feel stressful when a bill arrives.
That matters because pet costs are rising while household budgets stay tight. The American Pet Products Association reports that U.S. pet industry spending reached $158 billion in 2025, and it projects $165 billion for 2026. More importantly, its research found that 22% of pet owners spent less on their pets in 2025 as value-focused choices became more common. American Pet Products Association
When we approach budgeting for pet owners as a care plan rather than a spending restriction, we can protect our pets' needs without letting every expense disrupt the rest of our financial life.
Start With a Pet Budget That Separates Predictable and Unpredictable Costs
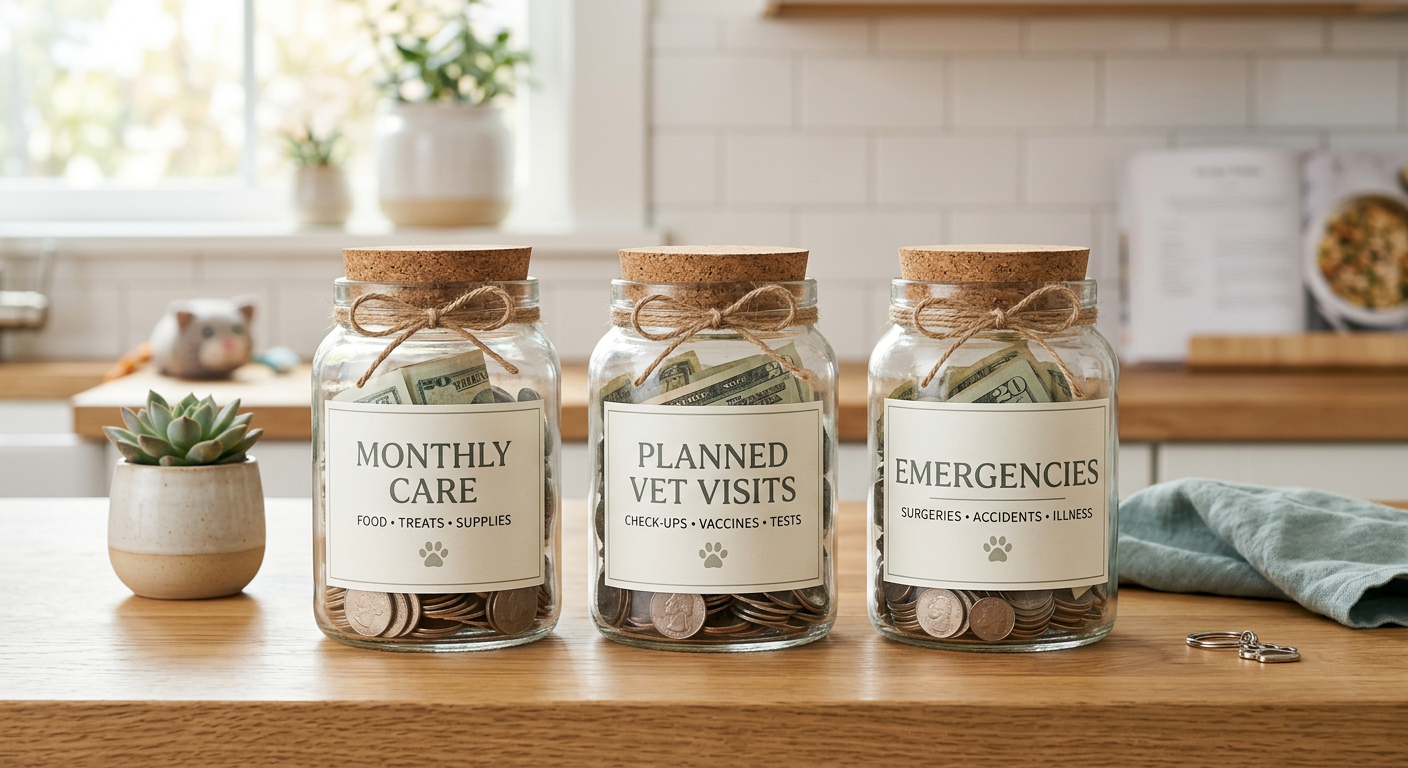
The most useful pet budget has two jobs: it pays for regular needs each month and prepares for expenses that do not arrive on schedule. Combining everything into one vague category makes it hard to see what is truly affordable.
Use these three buckets to organize spending:
| Budget bucket | Typical expenses | How to fund it |
|---|---|---|
| Monthly essentials | Food, litter, medication, treats | Monthly checking budget |
| Planned annual care | Wellness visits, vaccines, grooming, licensing | Monthly sinking fund |
| Emergency care | Injury, illness, urgent diagnostics | Emergency fund or insurance |
For example, if annual routine veterinary care, grooming, and supplies are likely to total $720, set aside $60 each month. That amount stays available when an annual exam or dental cleaning appears on the calendar instead of becoming an unexpected hit to a single paycheck.
This approach also shows where we can safely cut back. A less expensive toy may be fine. Skipping a prescribed medication or delaying a needed exam is a different decision entirely.
Build Your Number From Real Spending, Not a Generic Average
A realistic plan comes from our pet's actual needs, location, age, and health history. National averages can provide context, but they cannot predict the cost of a large-breed dog's food, a senior cat's medication, or boarding during a family trip.
For the next 30 days, track every pet-related transaction. Include the small purchases that are easy to dismiss, such as treats, delivery fees, replacement collars, nail trims, and automatic subscription renewals. Then review the list under four headings:
- Food and routine supplies
- Preventive health care
- Services, including grooming, walking, training, and boarding
- Optional purchases, including toys, accessories, and convenience items
After that first month, look back at the prior year for large or infrequent expenses. Add up vet bills, registration fees, parasite prevention, travel care, and any supplies purchased in bulk. Divide annual expenses by 12 and transfer that amount to a separate savings category each month.
The goal is not to predict every dollar perfectly. It is to replace guesswork with a flexible baseline we can update as our pet grows, ages, or develops new needs.
Use a Four-Level Spending Framework Before Cutting Costs
Not all pet expenses deserve the same priority. A clear hierarchy helps us reduce spending without compromising health, safety, or quality of life.
Level One: Health and Safety Essentials
These expenses come first: appropriately portioned food, clean water, preventive care, necessary medication, secure housing, identification, and prompt attention when a pet is sick or injured. We should discuss alternatives with a veterinarian if cost is a concern, but we should not make care decisions based only on a price tag.
Level Two: Care That Prevents Bigger Bills
Routine exams, dental care, training, grooming requirements, parasite prevention, and maintaining a healthy weight can prevent avoidable problems. We do not need the most premium option in every category, but consistency often costs less than reacting to a preventable issue later.
Level Three: Quality-of-Life Spending
Toys, enrichment activities, beds, scratching surfaces, treats, and occasional daycare belong here. These can be valuable, especially for active or anxious pets, but we can set a monthly cap and rotate what we already own before buying more.
Level Four: Convenience and Extras
Subscription boxes, matching accessories, impulse purchases, premium upgrades, and frequent professional services are optional. There is nothing wrong with enjoying them when our budget permits. The problem starts when extras quietly consume money reserved for routine care or emergencies.
Make Room for Emergencies Before One Happens
An emergency fund is often the difference between having choices and feeling forced into a rushed financial decision. We recommend building a dedicated pet reserve alongside a general household emergency fund.
Start with a manageable first target, such as $500, then increase it over time. Automating even $20 or $40 per payday creates momentum. If we receive a tax refund, bonus, gift, or refund from a returned item, consider assigning part of it to the reserve.
Pet insurance can also be part of the plan, but it is not automatically the best answer for every household. Compare monthly premiums, deductibles, reimbursement percentages, annual limits, exclusions, waiting periods, and coverage for pre-existing conditions. Insurance may suit owners who want protection from a high-cost medical event, while a well-funded reserve may suit households that prefer to self-fund risk.
The key is choosing one deliberate approach, or combining both. Paying for insurance without understanding coverage, or assuming a small savings balance will cover any emergency, can leave gaps when care is needed.
Save on Routine Care Without Choosing the Cheapest Option Blindly
The best savings usually come from comparing value, planning ahead, and asking useful questions. They do not come from buying unfamiliar products or delaying care until a problem becomes urgent.
Try these practical cost controls:
- Ask your veterinary clinic for a written estimate before non-urgent procedures.
- Request information about payment options, wellness plans, or lower-cost appointment times when available.
- Buy food and litter in sizes that we can use before expiration, not simply the largest package on the shelf.
- Compare unit prices, shipping fees, and auto-ship discounts before committing to subscriptions.
- Keep a simple inventory of food, medication, and supplies to avoid panic purchases.
- Learn safe at-home tasks, such as basic brushing and nail care, if our pet tolerates them and our veterinarian approves.
- Use pet sitters, boarding, and grooming services selectively, especially during high-expense months.
A good rule is to compare products by reliability and total cost, not by sticker price alone. A food that agrees with our pet, is nutritionally appropriate, and creates less waste can be a better value than a discounted alternative that causes digestive issues or gets left uneaten.
Create a Progressive Plan for Each Stage of Your Pet's Life
Budgeting works best when it evolves. A young pet, a healthy adult, and a senior animal create different demands on time, care, and money, so we should review the plan at least twice a year.
New Pets Need a Setup Fund
Adoption fees, initial exams, vaccines, spay or neuter procedures, microchipping, crates, carriers, training, bedding, and supplies can make the first few months expensive. Create a one-time setup category before bringing home a new pet, rather than assuming monthly cash flow will absorb it.
Adult Pets Need Consistency
For many adult pets, the focus shifts to steady food, preventive care, regular activity, and an emergency reserve. This is the best time to build savings because expenses may feel stable. Use that stability to prepare for later-life care rather than allowing every unused dollar to disappear into extras.
Senior Pets Need More Financial Flexibility
Older pets may need more frequent monitoring, prescription diets, mobility support, dental work, or specialty care. Review insurance coverage, emergency savings, and quality-of-life priorities before a health crisis forces a decision. A conversation with a veterinarian about likely future needs can help us budget with compassion and realism.
Hold a 15-Minute Pet Money Check-In Each Month
A short monthly review keeps the budget useful without making pet care feel like accounting homework. Schedule it near the same date each month and review four questions.
- Did we spend more or less than planned?
- Is an annual or seasonal expense coming up soon?
- Did our pet's health, food needs, or routine change?
- Can we move a little more into the emergency fund this month?
This small habit helps us spot patterns early. Maybe a subscription is no longer useful, food prices increased, or grooming is becoming a recurring need. A budget should be adjusted when life changes, not treated as a test we fail when expenses shift.
Frequently Asked Questions
How much should we save for a pet emergency?
A sensible first target is $500, then build toward an amount that reflects our pet's species, age, health, and local veterinary costs. If that feels out of reach, start with a small automatic transfer and pair it with a careful review of insurance options.
Is pet insurance cheaper than paying out of pocket?
It can be, but only when the policy's coverage and our pet's medical needs align. Review the deductible, reimbursement rate, annual limit, waiting periods, and exclusions before assuming a low premium provides broad protection.
Can we use a credit card for veterinary bills?
A credit card can provide short-term flexibility, but it is risky as a primary emergency plan if the balance cannot be paid quickly. High interest can turn a stressful vet bill into a long-term debt problem, so build savings and understand payment options in advance.
Should food, treats, and toys share one budget category?
They can, but separating essentials from discretionary purchases gives us better control. Food belongs in the essentials category, while treats and toys should have a smaller flexible limit that we can reduce when another expense rises.
What if our pet budget is already stretched?
Start by protecting essentials and reviewing recurring charges, convenience spending, and unused services. Then ask a veterinarian about lower-cost options that still meet your pet's needs, rather than postponing care without guidance.
How often should we update a pet budget?
Review it monthly and reassess the full plan every six months. Update it immediately after a health diagnosis, move, change in income, adoption of another pet, or major change in food or care needs.
Put Your Pet Budget Into Action This Week
We do not need a perfect spreadsheet to make meaningful progress. List last month's pet expenses, choose one monthly savings amount for planned care, and set up a separate emergency category before the week ends.
For more practical articles that connect personal finance, healthier routines, and everyday pet care, visit ContentBeast. We can use clear information and small, repeatable habits to make responsible pet ownership feel more manageable.
A Stronger Budget Creates More Peace of Mind
Budgeting for pet owners is ultimately about being prepared to care well, not about removing every enjoyable purchase. When we separate essentials from extras, save gradually for routine and urgent care, and revisit the plan as our pet's needs change, money becomes one less source of uncertainty.
Our pets depend on us, and a clear plan lets us show up for them with more confidence. Start small, stay consistent, and let each monthly check-in make the next one easier.