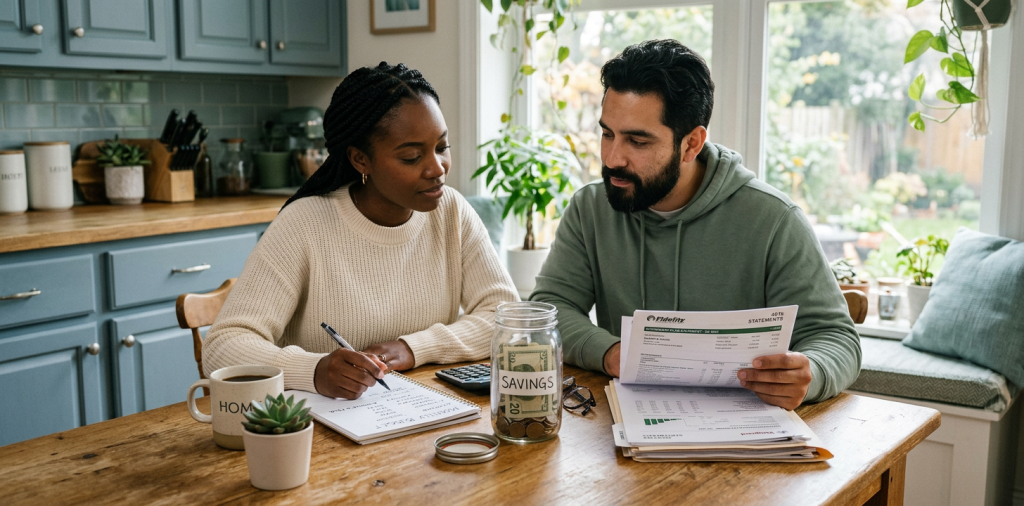
Money plans rarely fail because someone does not understand that saving is important. They fail because rent, student loans, changing jobs, health costs, family responsibilities, and everyday spending all compete for the same paycheck.
That is why financial planning for millennials should start with a flexible system, not a rigid list of rules. We need a plan that handles real life, protects us from predictable surprises, and still leaves room for goals that make life feel worthwhile.
A recent Federal Reserve report found that 55% of U.S. adults had enough emergency savings to cover three months of expenses in 2025. The same report found that only 35% of non-retired adults felt their retirement savings were on track. Those figures make the priority clear: build stability first, then automate long-term progress.
Start With a One-Page Money Map
A useful money map shows where each dollar needs to go before we decide what to cut or invest. It replaces vague financial anxiety with a short list of decisions we can review each month.
| Priority | What It Covers | First Target | How Often to Review |
|---|---|---|---|
| Essentials | Housing, food, utilities, insurance | Keep within income | Monthly |
| Safety net | Emergency fund, deductibles | One month of core costs | Monthly |
| High-cost debt | Credit cards, payday loans | Pay above minimums | Every payday |
| Future wealth | Workplace plan, IRA, investing | Capture employer match | Quarterly |
| Life goals | Travel, home, family, career change | Separate savings buckets | Monthly |
Start by listing net monthly income, fixed bills, minimum debt payments, variable essentials, and annual expenses that are easy to overlook. Car registration, gifts, subscriptions, pet care, insurance premiums, and medical copays are not surprises when we put them on the map.
Then calculate a basic cash-flow number: income minus required spending. If it is negative, investing more aggressively is not the first move. We should reduce costs, increase income, adjust debt payments where possible, or use a temporary spending plan before adding new financial goals.
Build a Safety Net Before Chasing Perfect Returns
Emergency savings give us choices when life gets expensive. The goal is not to earn the highest return possible with this money. The goal is to avoid turning a car repair, vet bill, layoff, or urgent flight into high-interest debt.
We recommend keeping emergency money in an insured, accessible savings account rather than in stocks or a long-term retirement account. Start with a smaller milestone if three to six months of expenses feels distant. A first target of $500 or $1,000 can cover many immediate disruptions and creates momentum.
Define Your Personal Emergency Number
Use core monthly expenses, not total lifestyle spending. Include housing, groceries, utilities, insurance, transportation, minimum debt payments, medications, and necessary child or pet expenses. Leave out expenses you would pause during a true income interruption, such as streaming services, dining out, and nonessential shopping.
If our core expenses are $3,000 per month, a one-month fund is $3,000. A three-month fund is $9,000. That number may look substantial, but it becomes manageable when we break it into automatic weekly or paycheck-based transfers.
Keep Sinking Funds Separate
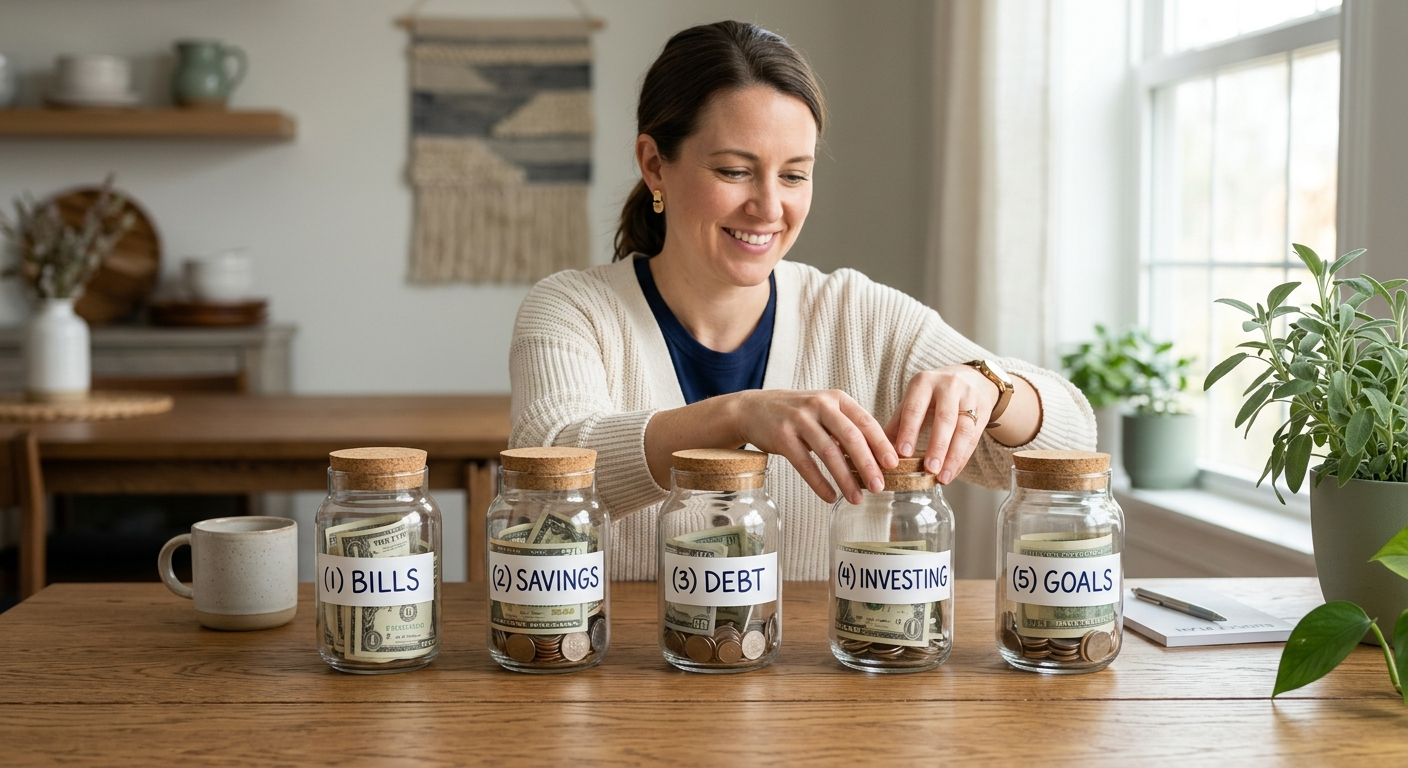
A sinking fund is money set aside for an expected future cost. It is different from an emergency fund because the expense is anticipated. We can create separate buckets for annual insurance, holiday gifts, home repairs, continuing education, travel, or replacing an aging car.
This separation matters. Using emergency savings for predictable expenses can make us feel as if we are constantly falling behind, even when the real issue is that irregular bills were never assigned a monthly amount.
Day 6: Use a Weekly Reset to Keep the Plan Realistic
The most sustainable plan is reviewed often enough to stay relevant, but not so often that it becomes exhausting. For Day 6 of a recurring money routine, we recommend a 20-minute weekly reset.
Choose the same day each week. Open your bank and credit card accounts, review upcoming bills for the next 10 days, check whether any spending category is drifting, and move money into sinking funds. This is also the moment to decide if a purchase belongs in the current week or should wait.
A weekly reset works well for millennials because income and spending can be uneven. Freelance projects, bonuses, childcare changes, travel, side gigs, medical costs, and shared household expenses can make a once-a-month budget feel outdated almost immediately.
Use this simple Day 6 checklist:
- Confirm account balances and upcoming automatic payments.
- Compare actual spending with the amount available until the next payday.
- Pay an extra amount toward high-interest debt, even if it is modest.
- Transfer a fixed amount to emergency savings or a sinking fund.
- Review one future goal, such as retirement contributions or a planned move.
- Name one expense you can avoid next week without making life miserable.
The goal is not perfect compliance. The goal is to spot problems while they are still small enough to solve.
Pay Down Expensive Debt With a Clear Order
High-interest debt can undermine every other financial goal because the interest compounds against us. Credit card balances, payday loans, and some personal loans generally deserve urgent attention once we have a small cash buffer.
List every debt with its balance, interest rate, minimum payment, and due date. Continue paying the minimum on all accounts, then put extra cash toward one target debt. The avalanche approach targets the highest interest rate first, which usually minimizes total interest. The snowball approach targets the smallest balance first, which can create faster psychological wins.
Neither method is morally superior. We should choose the approach we are most likely to sustain for a year or more. If a balance has a promotional rate ending soon, or a loan carries a penalty or collection risk, adjust the order accordingly.
Protect Your Credit Without Obsessing Over It
Pay on time, keep credit utilization low when possible, and avoid opening accounts solely for a temporary discount. Set bill reminders or automatic minimum payments to protect against missed due dates, then schedule additional payments manually.
If payments are becoming unmanageable, contact the lender before missing payments. A hardship plan, adjusted payment date, or nonprofit credit counseling option may be more useful than trying to solve the problem with another loan.
Invest Early, Simply, and Consistently
For long-term goals, consistency usually matters more than finding a perfect investment idea. We can begin with a workplace retirement plan, especially when an employer offers a matching contribution, and increase contributions gradually as income rises.
If a workplace plan is unavailable or we want additional retirement savings, an IRA may be worth evaluating. Traditional and Roth accounts have different tax treatment and eligibility rules, so the right choice depends on income, current taxes, future expectations, and plan options. A qualified tax professional or fiduciary financial planner can help with decisions that affect taxes or major life changes.
For many people, diversified low-cost index funds or target-date funds offer a straightforward foundation. They are not risk-free, but they avoid concentrating all long-term savings in a single stock, trend, or speculative asset.
Give Every Goal Its Own Time Horizon
Money needed within the next few years should generally prioritize stability and access. A home down payment, wedding, career break, or near-term relocation fund should not rely on stock-market gains arriving on schedule.
Money for retirement decades away can usually tolerate more short-term fluctuation. Separating goals by timeline prevents us from raiding retirement accounts for expenses that should have had a dedicated savings bucket.
Make Room for Health, Happiness, and the Life You Want
A financial plan should support well-being rather than reduce life to spreadsheets. We can set a realistic amount for fitness, preventive care, therapy, hobbies, travel, or time with friends without pretending those priorities do not exist.
The key is intentionality. A gym membership we use, quality groceries that support our health, or a mindfulness app that helps us sleep may be valuable spending. Repeated purchases that do not improve our life are the better place to look for cuts.
For households with pets, include routine veterinary care, food, grooming, medications, and an emergency reserve in the plan. For parents and caregivers, build in childcare, school costs, and care-related travel. A budget reflects real responsibilities, not an imaginary version of our lives.
Common Questions About Millennial Money Planning
How much should millennials save each month?
We should save an amount we can repeat consistently, even if it starts small. Begin by automating a percentage of each paycheck, then raise it after a pay increase, a debt payoff, or a reduction in fixed expenses.
Should we invest while paying off credit card debt?
Usually, we should prioritize high-interest credit card debt after building a small emergency cushion and capturing any employer retirement match. The interest avoided by eliminating costly revolving debt can be more valuable than taking additional investment risk.
Is a three-month emergency fund enough?
Three months is a strong baseline, but the right amount depends on job stability, household size, insurance deductibles, health needs, and income variability. Freelancers, single-income households, and people in volatile industries may prefer a larger reserve over time.
Should we use a budgeting app or a spreadsheet?
Use the tool that makes us review our money regularly. Apps can automate transaction tracking, while a spreadsheet offers more control and privacy. The habit of reviewing the numbers matters more than the format.
What if we feel behind on retirement savings?
Feeling behind is common, but it is more useful to focus on the next contribution than on a comparison chart. Capture any employer match, automate contributions, increase them gradually, and avoid withdrawing retirement money for short-term spending when alternatives exist.
Can we plan financially with irregular income?
Yes, but the plan should be based on a conservative income floor rather than the best month of the year. Cover essentials from that baseline, build a larger cash reserve, and direct unusually strong months toward taxes, debt, savings, and future goals.
Build a More Confident Money Routine
A lasting money plan is built through repeatable decisions, not one dramatic overhaul. Explore the personal finance, wellness, sleep, and everyday-life resources at Content Beast to keep building routines that support both your financial goals and your quality of life.
The Plan That Works Is the One We Keep Using
Financial planning for millennials does not require a flawless budget, an extreme lifestyle, or constant market watching. It requires a clear view of cash flow, a growing safety net, a deliberate debt strategy, and automatic progress toward long-term goals.
Start with one action this week: create the one-page money map, schedule the weekly reset, or automate a small transfer into savings. Small systems become powerful when we give them time to work.