Building wealth through the stock market rarely requires a brilliant prediction or a perfectly timed trade. It requires a clear goal, money you will not need soon, a diversified approach, and the patience to continue when headlines become noisy.
For investing for beginners stock market questions, the most useful starting point is not picking a hot stock. We begin by protecting short-term finances, defining what the money is for, and choosing an investment approach we can stick with through both rising and falling markets.
This is educational information, not individualized financial advice. Your income, debt, tax situation, time horizon, and comfort with risk all matter, so consider a qualified financial professional when decisions feel complex.
What Beginner Stock Market Investing Should Look Like
Beginner investing should be boring enough to repeat. We want a simple system that puts long-term goals ahead of market predictions, social media excitement, or daily price changes.
| Priority | What It Means | Beginner-Friendly Move |
|---|---|---|
| Financial base | Cash needs come first | Build emergency savings |
| Time horizon | Match risk to timing | Invest money needed years away |
| Diversification | Avoid one-company risk | Consider broad funds |
| Consistency | Reduce emotional decisions | Automate regular contributions |
| Cost control | Fees reduce returns | Compare fund expenses |
Stocks represent ownership in companies. Their prices can rise or fall sharply in the short term, but stocks have historically offered higher potential returns, along with higher risk, than bonds or cash. The U.S. Securities and Exchange Commission notes that large-company stocks have lost money on average about one out of every three years, which is a useful reminder that volatility is normal, not proof that a long-term plan has failed. Investor.gov
A stock market plan works best when it reflects the date you need the money. A vacation fund or home down payment needed soon generally calls for less market risk than a retirement goal decades away. We do not treat every dollar as if it has the same job.
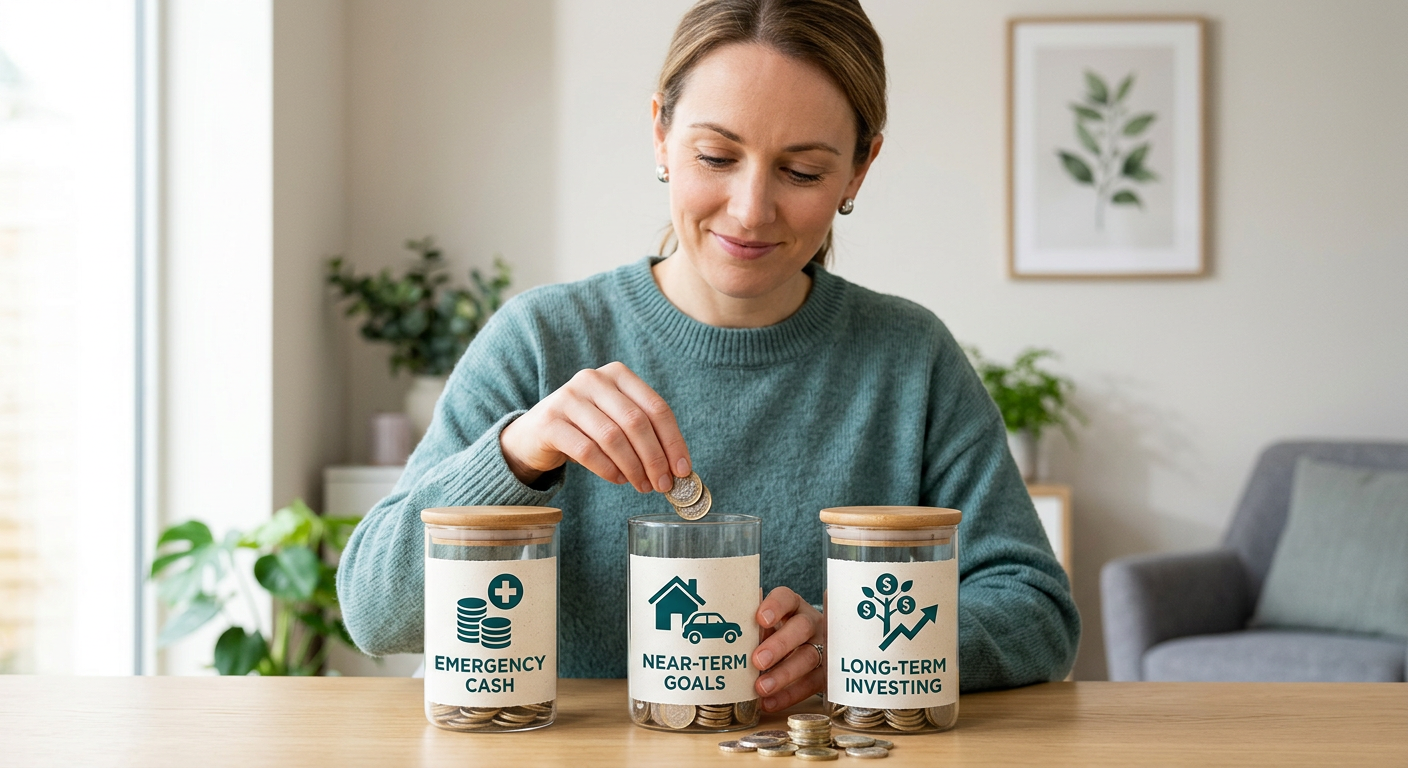
Prepare Your Financial Base Before Buying Shares
A strong financial base makes it easier to stay invested when life gets expensive or markets decline. Before we invest heavily in stocks, we should address costly debt, create a cash buffer for emergencies, and confirm that our regular expenses are manageable.
High-interest credit card debt can outpace the return we might reasonably expect from investing, while an emergency fund may prevent us from selling investments at a loss after an unexpected car repair or medical bill. The goal is not to wait until every financial detail is perfect. It is to avoid using a stock portfolio as a checking account.
Put a Purpose and Date on Each Goal
Goals convert vague intentions into better decisions. Instead of saying, “We want to invest more,” define a target such as retirement in 25 years, a child's education in 15 years, or financial flexibility in 10 years.
Then ask two practical questions:
- When will we need this money?
- How would we respond if its value fell 20% or more for a period of time?
Our answers help determine how much stock exposure may suit the goal. Longer timelines can usually absorb more market fluctuation than short timelines, but no investment mix eliminates risk.
Choose Diversification Over a Single “Winner”
For most new investors, broad diversification is a more durable foundation than attempting to identify the next breakout company. Owning a wide range of companies, sectors, and sometimes countries reduces the damage one poor performer can do to the portfolio.
A diversified mutual fund or exchange-traded fund can hold shares in hundreds or thousands of companies. That is very different from buying a few familiar brand names and hoping each one performs well. Investor.gov explains that a total stock market index fund can provide ownership across thousands of companies, though even a fund should be reviewed to understand what it holds and what it costs. Investor.gov
There is another reason simple, broad investing appeals to many beginners. In S&P Dow Jones Indices' year-end 2025 scorecard, 79% of actively managed large-cap U.S. equity funds underperformed the S&P 500 during that year. That result does not guarantee what will happen next, but it illustrates why low-cost, diversified index investing deserves serious consideration before we chase stock-picking claims. S&P Dow Jones Indices
Understand the Main Account Choices
The account matters alongside the investment. An employer retirement plan may include matching contributions, while an individual retirement account can offer tax advantages depending on eligibility and account type. A taxable brokerage account offers flexibility but does not provide the same tax treatment as retirement accounts.
We can start by checking whether an employer match is available, reviewing plan fees and choices, and learning the withdrawal rules before committing money. If we use a brokerage account, we should confirm that it is regulated, understand its pricing, and keep account security strong with unique passwords and multifactor authentication.
Build a Day 7 Routine That Keeps Emotion Out
A recurring weekly routine can stop beginner investors from turning every market headline into a trade. On Day 7, we review our system, not the market's latest drama.
Set aside 15 minutes once each week for this checklist:
- Confirm that bills, debt payments, and emergency savings remain on track.
- Check that an automatic contribution occurred or schedule the next one.
- Review one concept, such as expense ratios, dividends, taxes, or asset allocation.
- Do not make an investment change unless a goal, timeline, income, or risk capacity actually changed.
This progressive approach is deliberately modest. In the first week, our job is to establish the habit and vocabulary. Later, we can learn how fund fees work, how to rebalance, and how taxes affect a taxable account. Each layer builds on the last without demanding that we become full-time market analysts.
Dollar-cost averaging can fit this routine well. It means investing equal amounts at regular intervals regardless of market ups and downs, which can reduce the pressure to decide whether this week is the perfect time to buy. Investor.gov
Keep Costs, Hype, and Trading Friction in Perspective
Small recurring costs can quietly weaken long-term results, so we should compare expense ratios, account fees, and transaction charges before investing. A fund with a low price per share is not automatically inexpensive, and a fund with a high recent return is not automatically suitable.
We should also be skeptical of anyone promising guaranteed returns, urgent stock picks, or secret methods for beating the market. Legitimate investing includes uncertainty. A sound plan is designed around that uncertainty rather than pretending it does not exist.
Common Beginner Mistakes We Can Avoid
The most expensive investing mistakes often come from behavior, not a lack of intelligence. We can reduce the odds of making them by writing down our rules before the next market drop.
- Investing emergency money in stocks
- Buying a stock because it is trending online
- Holding too much of one company or industry
- Ignoring fund expenses and account fees
- Selling after a market decline without revisiting the original goal
- Checking balances so often that anxiety drives decisions
Compounding rewards consistency and time. Investor.gov uses an illustration in which investing $100 monthly for 40 years at an assumed 7% average annual return can grow substantially, but the key word is assumed. Actual returns vary, and the illustration is useful for understanding the role of time, not for predicting a personal outcome. Investor.gov
Frequently Asked Questions
How much money do we need to start investing?
We do not need thousands of dollars to begin, especially when a workplace plan or brokerage allows small recurring contributions. The right amount is one that fits the budget after essential expenses, high-interest debt priorities, and emergency savings needs.
Is it better to buy individual stocks or funds as a beginner?
Broad, diversified funds are often easier for beginners because one purchase can spread money across many companies. Individual stocks may be appropriate for a small learning allocation, but concentrating most of a portfolio in a few names adds significant company-specific risk.
Can we lose all our money in the stock market?
A diversified portfolio can lose value, sometimes sharply, but spreading investments across many companies and asset types reduces the risk tied to any one company failing. A single stock can become worthless, which is why diversification matters.
How often should we check an investment account?
For a long-term plan, monthly or quarterly checks are often enough to confirm contributions, fees, and allocation. Daily monitoring can make normal volatility feel like a problem that demands action.
What is the difference between an ETF and a mutual fund?
Both can hold many underlying investments and help with diversification. ETFs generally trade during the market day like stocks, while mutual funds typically transact once daily after the market closes; each can have different minimums, fees, and tax considerations.
Should we pause investing when the market falls?
A market decline does not automatically mean we should stop a long-term contribution plan. We should first confirm that our emergency cash, goals, and risk tolerance are still appropriate, then avoid making a fear-driven change based solely on short-term price movement.
Build Confidence Through Process, Not Predictions
The stock market can support long-term goals, but it is not a shortcut or a certainty. The strongest beginner plan is usually the one we understand, can afford to maintain, and will not abandon when markets become uncomfortable.
Start with financial stability, use diversification to limit avoidable risk, keep costs visible, and invest regularly according to a goal-based plan. Over time, a calm process can matter far more than the excitement of finding a single winning stock.
Keep Building Your Money Skills
Learning personal finance works best when each lesson leads to a useful next step. Visit ContentBeast for clear articles on money habits, health, sleep, pets, and everyday well-being, then choose one small action to apply this week.