Building a retirement plan can feel complicated when every account seems to come with its own tax rules, limits, and fine print. A Roth IRA stands out because it asks you to pay taxes upfront, then potentially gives you decades of tax-free growth and qualified withdrawals later.
At its core, a Roth IRA is an individual retirement account funded with money you have already paid income taxes on. It can be a practical complement to a workplace 401(k), especially for people who expect their income or tax rate to rise over time. The key is understanding both the upside and the rules before you contribute.
The Roth IRA in Plain English
A Roth IRA is a tax-advantaged account you open yourself through a brokerage, bank, robo-advisor, or similar financial institution. You contribute after-tax dollars, choose investments inside the account, and qualified withdrawals in retirement are generally federal income tax-free.
Unlike a savings account, a Roth IRA is not the investment itself. It is the container. Inside it, you might hold diversified index funds, mutual funds, exchange-traded funds, bonds, or other investments offered by your provider. The U.S. Securities and Exchange Commission notes that IRAs are tax-advantaged investment accounts, and the provider you select determines the investment choices available to you. (investor.gov)
| Feature | Roth IRA | Traditional IRA | Traditional 401(k) |
|---|---|---|---|
| Contribution tax treatment | After-tax | Often deductible | Pre-tax payroll deferrals |
| Qualified retirement withdrawals | Generally tax-free | Generally taxable | Generally taxable |
| Income limit to contribute | Yes | No contribution limit | No income limit |
| Required withdrawals for original owner | No | Yes | Usually yes |
| Investment control | Broad, provider-dependent | Broad, provider-dependent | Limited by plan menu |
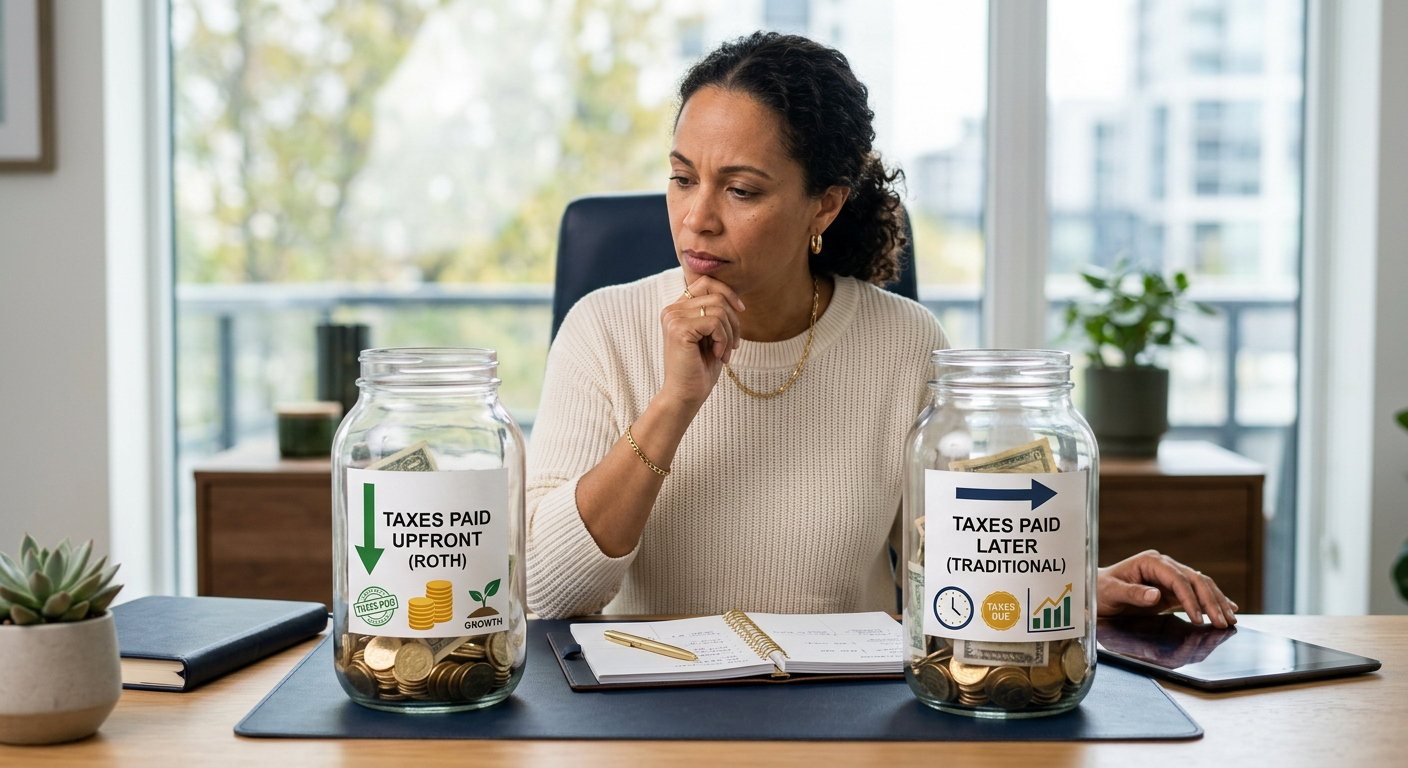
The tradeoff is straightforward. You give up a tax deduction for your contribution this year in exchange for the possibility of tax-free qualified income later. For many people early in their careers, that tradeoff can be appealing.
How a Roth IRA Works
You contribute money you have already paid taxes on
When your paycheck reaches your bank account, income taxes have generally already been withheld or will be addressed when you file your return. You use that after-tax money to fund the account. Roth IRA contributions are not tax-deductible.
The potential reward arrives later. If you meet the IRS requirements for a qualified distribution, both your contributions and investment earnings can be withdrawn without federal income tax. (irs.gov)
Your investments can grow without annual tax drag
Within a regular taxable brokerage account, you may owe taxes on dividends, interest, and realized investment gains along the way. Within a Roth IRA, those annual tax consequences generally do not apply while the money stays in the account.
That does not guarantee an investment profit. Markets can decline, and every investment involves risk. But shielding long-term compound growth from federal income tax can be meaningful, particularly when you give the account many years to grow.
Qualified withdrawals follow two main rules
For earnings to come out tax-free, you generally must satisfy the five-year holding period and meet a qualifying event. The most common qualifying event is reaching age 59½, although disability, death, and certain first-time homebuyer withdrawals can also qualify under IRS rules.
The first-time homebuyer exception is limited to a lifetime maximum of $10,000. It is useful to know about, but we would not build a retirement strategy around treating a Roth IRA like a down-payment account. (irs.gov)
Roth IRA Contribution Limits and Income Rules for 2026
For the 2026 tax year, the combined amount you can contribute across all of your traditional and Roth IRAs is generally $7,500. If you are age 50 or older, the limit is generally $8,600. You also cannot contribute more than your taxable compensation for the year. (irs.gov)
Direct Roth IRA contributions are subject to income limits based on modified adjusted gross income, often called MAGI. For 2026, the phaseout range is $153,000 to $168,000 for single filers and heads of household, and $242,000 to $252,000 for married couples filing jointly. Married taxpayers filing separately who lived with a spouse during the year have a much narrower $0 to $10,000 phaseout range. (irs.gov)
These limits can change from year to year, so it is worth checking the IRS rules before funding an account. If your income lands in a phaseout range, do not guess at the permissible contribution amount. A tax professional or a reputable contribution calculator can help you avoid an excess contribution.
A simple contribution example
Suppose you earn $60,000, have eligible compensation, and qualify to make the full contribution. You contribute $7,500 to a Roth IRA and invest it in a low-cost diversified fund. You do not deduct that $7,500 on your tax return, but future qualified withdrawals may be tax-free.
You do not need to fund the full amount in one deposit. A monthly automatic contribution of $625 would total $7,500 over a full year. For most households, consistency is more important than finding a perfect moment to invest.
When a Roth IRA May Make Sense
A Roth IRA can be especially useful when your current tax rate is relatively low compared with the rate you expect to face later. That often includes early-career professionals, people returning to work after time away, or anyone having an unusually low-income year.
It can also make sense if you want more tax flexibility in retirement. Having some money in pre-tax accounts and some in Roth accounts may allow you to manage taxable income more deliberately when you stop working.
You want flexibility around future withdrawals
Original Roth IRA owners do not have required minimum distributions during their lifetime. That means you are not forced to withdraw money at a specific age just because the government requires it, which can make the account valuable for estate planning and late-retirement tax management. (irs.gov)
You have earned income but no workplace retirement plan
A Roth IRA can give you a simple way to begin investing for retirement even if your employer does not offer a 401(k). Opening an account is usually straightforward, and you control where it is held and what it invests in.
You are already contributing to a 401(k)
A workplace match should often receive priority because matching contributions are part of your compensation. After capturing the full match, a Roth IRA can provide additional tax diversification and usually a wider investment selection than an employer plan.
For more practical money habits and long-term planning ideas, we can also explore the personal-finance guides published throughout this site.
Important Roth IRA Rules to Avoid Costly Mistakes
The flexibility of a Roth IRA is real, but it should not be mistaken for a general-purpose emergency fund. The account is designed for long-term retirement investing.
Contributions and earnings are treated differently
You can generally withdraw your regular Roth IRA contributions at any time without tax or penalty because you already paid tax on that money. Earnings are different. Taking earnings before a qualified distribution can lead to income taxes and potentially an additional 10% tax unless an exception applies. (irs.gov)
In practice, keep an emergency fund outside your retirement account. That separation helps protect your future investments when an unexpected car repair, medical bill, or job disruption occurs.
A Roth IRA is different from a Roth 401(k)
The names are similar, but the accounts have different rules. A Roth 401(k) is part of an employer-sponsored plan and uses payroll deductions, while a Roth IRA is an account you open independently. A Roth 401(k) also does not have the same direct contribution income limits, though plan rules and annual employee contribution limits still apply.
You may be able to use both if your budget supports it. The right mix depends on your employer match, tax situation, investment options, and savings goals.
Conversions are not the same as contributions
A Roth conversion moves money from a traditional retirement account into a Roth IRA. The converted pre-tax amount is generally taxable in the year of conversion, but the direct Roth IRA income limits do not prevent you from completing a conversion.
Conversions can be powerful in the right circumstances, but they can also create a larger tax bill. This is one area where individualized tax advice matters, especially if you are close to an income threshold or receive health insurance subsidies tied to income.
How We Would Open and Fund a Roth IRA
First, choose a reputable provider with low account fees, a strong selection of diversified funds, and an easy-to-use platform. Then open a Roth IRA, connect your bank account, and set a contribution amount you can sustain.
Next, choose investments that match your timeline and tolerance for market swings. For a retirement goal decades away, many investors use a diversified stock index fund or a target-date retirement fund, but your choice should reflect your full financial picture.
Finally, automate the process. A contribution schedule tied to payday turns retirement saving into a routine rather than a monthly decision. Review your contribution amount after raises, debt payoff milestones, or major life changes.
This information is educational, not personalized tax, legal, or investment advice. If you have questions about eligibility, conversions, withdrawals, or investment selection, consult a qualified tax professional or fiduciary financial adviser.
Frequently Asked Questions
Is a Roth IRA worth it if we have a 401(k)?
Often, yes. We would generally evaluate the employer match first, then compare your 401(k) investment options and fees with the flexibility of a Roth IRA. Using both accounts can create more retirement savings capacity and tax diversification.
Can we have both a Roth IRA and a traditional IRA?
Yes. However, the annual IRA contribution limit is shared across both account types. In 2026, your total regular contributions to all traditional and Roth IRAs generally cannot exceed $7,500, or $8,600 if you are age 50 or older. (irs.gov)
Can we withdraw Roth IRA money whenever we want?
You can generally withdraw your regular contributions whenever you want. But withdrawing earnings before meeting the qualified-distribution rules may trigger taxes and an additional tax, so it is wise to treat the account as retirement money. (irs.gov)
Do we pay taxes when we withdraw from a Roth IRA?
Qualified Roth IRA withdrawals are generally federal income tax-free. To be qualified, the distribution generally must meet the five-year rule and occur after age 59½ or another qualifying event such as disability, death, or a qualifying first-time home purchase. (irs.gov)
What happens if our income is too high for a Roth IRA?
You may be eligible for only a reduced direct contribution, or none at all, depending on your MAGI and filing status. Some higher-income households explore a Roth conversion strategy, but pro-rata tax rules can make the result more complicated than it appears.
Does a Roth IRA reduce our taxes this year?
No. Roth IRA contributions are made with after-tax dollars and generally are not deductible. The potential tax benefit comes later through tax-free qualified withdrawals rather than an upfront deduction. (irs.gov)
Build a More Confident Financial Routine
Retirement planning works best when it is connected to the rest of your life, including your budget, health goals, family priorities, and daily habits. Visit Content Beast for practical articles that make personal finance, well-being, sleep, fitness, and everyday decision-making easier to understand.
The Bottom Line on Roth IRAs
A Roth IRA gives you a clear tradeoff: pay taxes on contributions upfront, then position your investments for tax-free qualified withdrawals later. It can be a particularly strong tool when you have earned income, expect higher future tax rates, and can leave the money invested for years.
The best next step is not necessarily contributing the maximum amount. It is confirming your eligibility, choosing a low-cost provider, investing in a diversified way, and making a contribution schedule you can maintain. Small, consistent actions can make retirement planning feel far more manageable over time.